| EVERGREEN MARKET REPORT |
OCTOBER 2026 |
Alford-Bon | Tim & Faye | Sell · Buy · Invest
| |
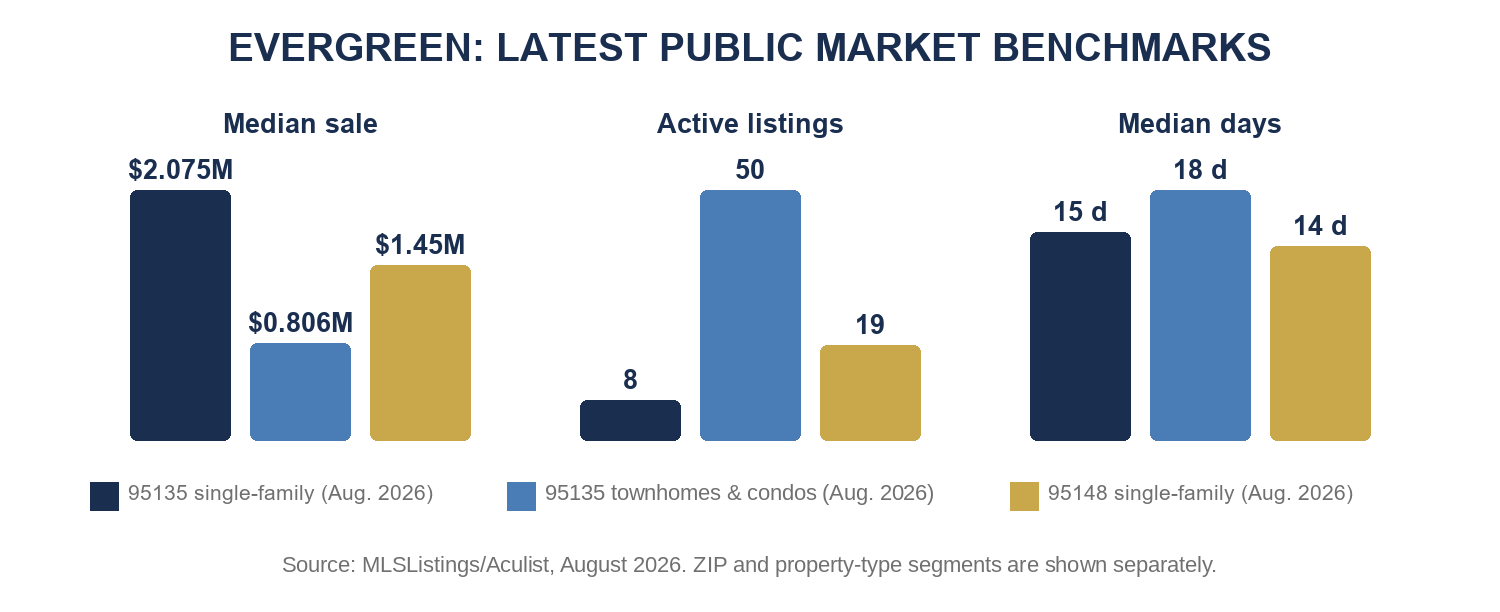
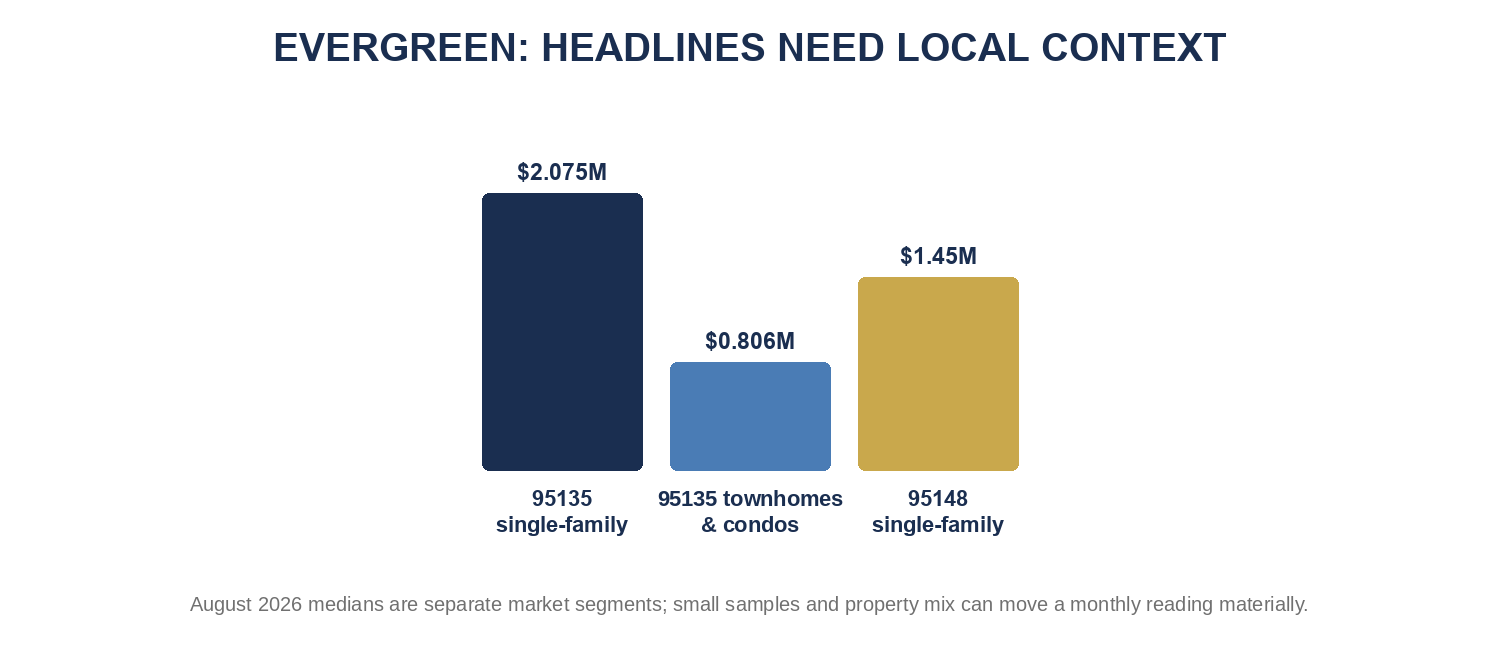
What changed since last month: financing tightened again, while Evergreen's conventional, age-restricted, HOA and luxury/view segments continued to behave as separate markets. 95135 single-family: $2.075M median, 6 closings, 15 median days, 100% of list; 95135 townhomes and condos: $0.806M median, 10 closings, 18 median days, 99% of list; 95148 single-family: $1.45M median, 17 closings, 14 median days, 100% of list.
The $2.075M primary benchmark is not a valuation for every home in Evergreen. Street setting, school assignment, lot utility, condition, permits, HOA structure, and the specific competing set can move an individual result materially. The most surprising readings - 95135 single-family (-28.4% year over year) - come from a small number of monthly sales and are treated as results that can be distorted by which homes happened to sell, not uniform changes in value. The decision-useful question is not whether the entire area is strong or weak. It is which homes are earning urgency, which have become alternatives, and whether the reported monthly sample actually resembles the property being evaluated.
What this means:
- Homeowners and sellers: Compare The Villages, Silver Creek, conventional neighborhoods, and luxury or view homes separately, then narrow by housing type, condition, HOA obligations, and location. One Evergreen median is not enough.
- Buyers: Only six 95135 houses closed. Compare the home within The Villages, Silver Creek, or its true neighborhood, watch for a price change, missed offer date, or return to market, and confirm the seller's timing before seeking price or terms.
- Tim & Faye
|
|
|
Evergreen Market
The Local Pulse
|
|
August 2026 at a glance
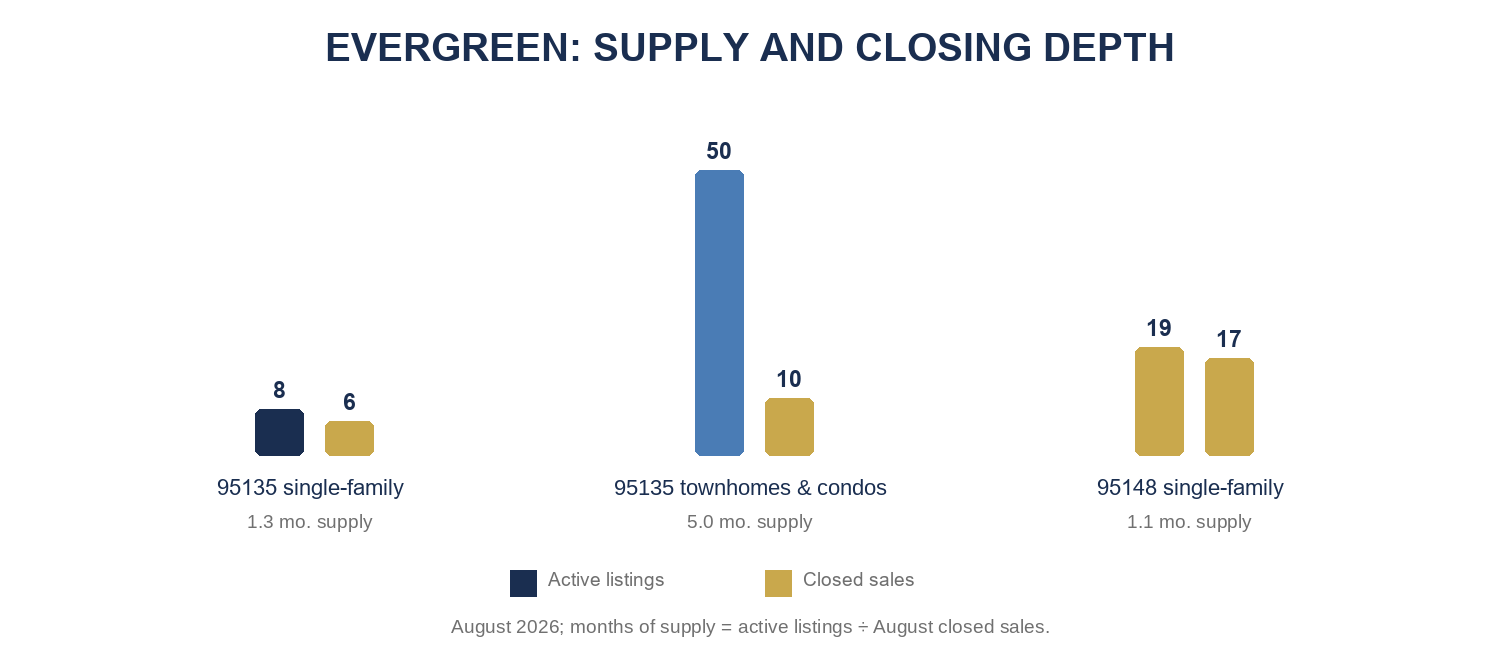
- Primary benchmark: 95135 single-family: $2.075M median; 6 closings; 15 median days; 100% sale-to-list; 1.3 months of inventory.
- Comparison signal: 95135 townhomes and condos: $0.806M median; 10 closings; 18 median days; 99% sale-to-list; 5.0 months of inventory.
- Selection and pace: Sample and selection: 33 closings across the shown market segments and 77 active listings; medians can be distorted when only a few homes sold or the mix of homes changed.
- Financing: the national 30-year fixed average was 7.28% on October 1. At that rate, 20% down on the $2.075M benchmark implies roughly $11,360 per month in principal and interest before taxes, insurance, and other costs. Pricing can differ by loan and borrower.
|
|
Financing & Affordability
What the October Rate Picture Means
|
|
Freddie Mac's national 30-year fixed average was 7.28% on October 1. With 20% down on the $2.075M benchmark, the illustrative principal-and-interest payment is about $11,360 per month, before property tax, insurance or other obligations. This is a planning illustration rather than a loan quote; pricing, points and borrower profiles can differ materially. The Federal Reserve raised its target range by one-quarter point on September 16; mortgage rates do not move one-for-one with that policy rate, so buyers should compare the actual fixed-rate, adjustable-rate, and buydown quotes available for their loan size.
C.A.R.'s second-quarter affordability index found that 22% of Santa Clara County households could afford the county's $2.05 million median single-family home. Its model required about $510,800 in annual income at a 6.54% effective rate. Evergreen's townhomes, conventional houses, and luxury or custom homes attract buyers with different budgets, down payments, and financing options; one regional employment headline cannot explain demand for all of them.
Many buyers are using adjustable-rate mortgages or temporary buydowns to reduce the initial payment while preserving the opportunity to refinance if fixed rates improve. That can be practical for a buyer with strong liquidity, expected income growth, or a defined holding period, but the adjustment schedule, rate caps, and future payment range should be compared with a fixed-rate option before offer day.
A targeted seller credit can sometimes address payment pressure more efficiently than a broad price reduction. Buyers should compare that benefit with the property's immediate repair, insurance, and ownership costs.
|
|
Market Behavior
What Is Moving
|
|
Entry-priced condo — 5155 Cribari Knolls. The two-bedroom, two-bath, 1,240-square-foot condo closed August 21 for $535,000. It shows an Evergreen ownership entry point well below the single-family headline, but property type, HOA obligations, community restrictions, and condition remain essential to the comparison.
Near the single-family median — 3808 Thompson Creek Court. The five-bedroom, three-and-one-half-bath, 2,957-square-foot home closed August 19 for $2.15 million, close to August’s $2.075 million 95135 single-family median. It is a useful benchmark, not a substitute for comparing lot, condition, micro-location, and immediate competition.
Upper-market sale — 3307 Royal Meadow Lane. The four-bedroom, three-bath, 2,768-square-foot home closed August 18 for $2.6 million. The result shows that larger, well-located Evergreen homes can attract buyers with different budgets and priorities than a typical resale.
|
|
Market Behavior
Where Activity Stalls
|
|
Listings marketed against the wrong Evergreen median. Combining Silver Creek, The Villages, and conventional single-family homes produces misleading expectations.
Higher-fee or insurance-sensitive properties. HOA dues, assessments, master insurance, gates, and maintenance obligations affect total cost.
Remote-feeling locations without a strong price case. Buyers weigh commute time and daily convenience more heavily when inventory rises.
|
|
Regional Comparison
AI Wealth: Relevant, Not the Whole Story
|
|
Evergreen offers space, newer housing, foothill views, and school options at a range of price points. That breadth attracts several buyer pools, but it also makes a single regional wealth narrative less useful.
AI and technology wealth can support Silver Creek and high-end view properties, while the broader market remains governed by payment, commute, fees, and household utility.
| |
Our read: Evergreen's conventional single-family, age-restricted, HOA and luxury/view segments will continue to behave differently; one area median will not describe them well. |
|
|
What Changes Next
Local Community Watch
|
|
Jackson Avenue and I-680 is approaching a visible milestone. San José says construction began in early 2026 and signal activation is planned for fall. The project adds a traffic signal, signalized crosswalk, lighting and a curb extension at the southbound on-ramp.
Why residents should care. The intersection should become safer and easier to cross, although drivers and nearby households may experience temporary construction effects before the signal is activated.
What to watch next. Watch the activation date and post-opening traffic flow. This is a near-term access and safety improvement, not a housing-supply change.
|
|
Six-Month Outlook
Our Base-Case View
|
| Segment |
Expected direction |
Why |
| 95148 family homes |
Competitive |
17 August sales at 100% of list. |
| Conventional 95135 |
Selective |
Only six August sales; areas and home types vary. |
| Silver Creek luxury |
Property specific |
Condition, views, fees, and scarcity drive results. |
| The Villages |
Separate market |
Age restriction and HOA structure define demand. |
|
|
Prediction: Evergreen will remain a collection of distinct markets through early 2027. Strong family homes can sell quickly, while 95135's broader selection and product mix create more negotiation. Reported ZIP medians will continue to swing unless product categories are separated.
This is a market outlook, not a guarantee of future value. Property condition, micro-location, school assignment, lot, architecture, insurance, and financing can materially change an individual result.
|
|
Recommendations
What Matters Now
|
|
For homeowners:
- never use a blended 95135 median without separating The Villages, Silver Creek, and conventional housing.
- document HOA, insurance, gate, solar, roof, and exterior-maintenance obligations early.
- Do not use the 95135 year-over-year median drop as an area-wide value change: only six single-family homes closed, so compare the exact community and housing type before revising an estimate.
For sellers:
- identify whether the likely buyer is comparing The Villages, Silver Creek, a conventional neighborhood, or a luxury or view home, then price against the most similar recent sales and current listings.
- make commute, schools, views, outdoor space, and community amenities concrete and verifiable.
- Lead with the exact community's HOA, gate, solar, roof, insurance, and exterior obligations; buyers comparing The Villages, Silver Creek, and conventional homes will discount missing answers.
For buyers:
- Compare The Villages' age and HOA obligations, Silver Creek's gate and dues, and conventional-home commute costs; price per square foot cannot reconcile those ownership differences.
- Treat the 95135 median drop as a six-sale mix result, not a bargaining target; confirm value with the same community and housing type before setting the offer.
- Verify whether the home is in The Villages, Silver Creek, or a conventional neighborhood and price the HOA, age restriction, solar, insurance, and commute obligations; the same 95135 label can describe very different ownership.
|
|