| ALMADEN VALLEY MARKET REPORT |
OCTOBER 2026 |
Alford-Bon | Tim & Faye | Sell · Buy · Invest
| |
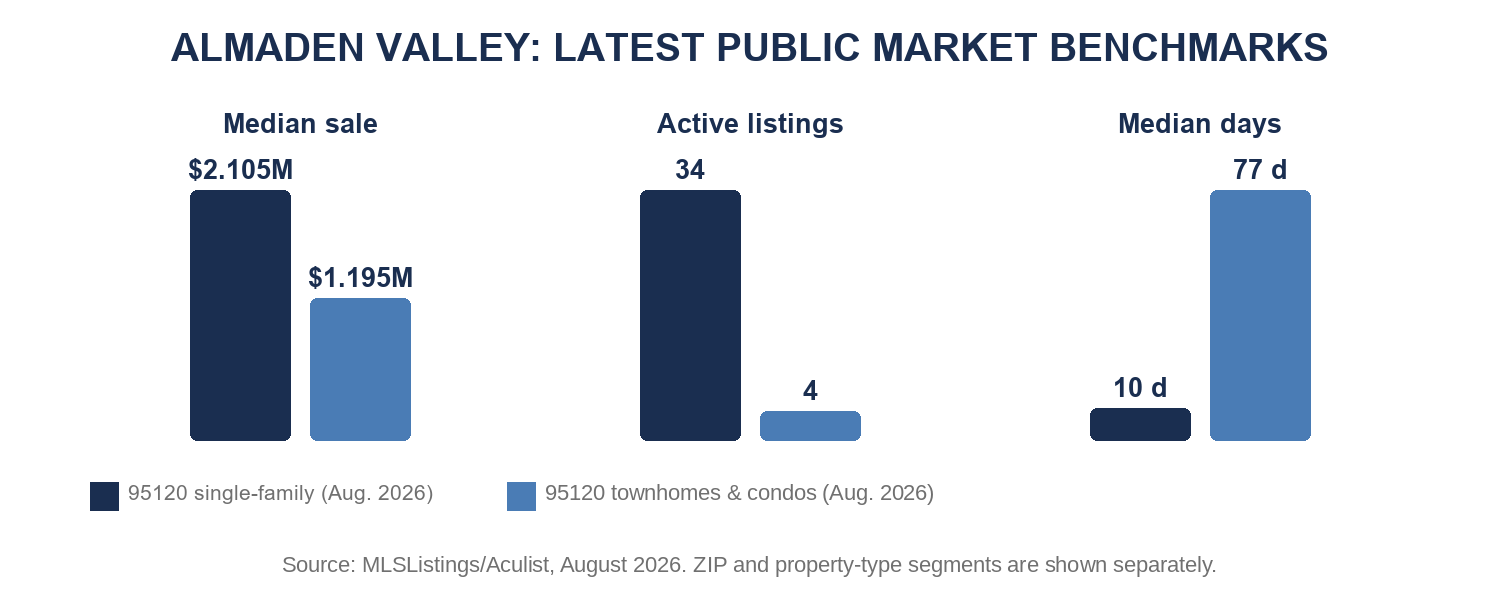
What changed since last month: financing tightened again, while Almaden Valley's best-prepared homes and its more complex properties continued to draw different buyer responses. 95120 single-family: $2.105M median, 23 closings, 10 median days, 101% of list; 95120 townhomes and condos: $1.195M median, 3 closings, 77 median days, 99% of list.
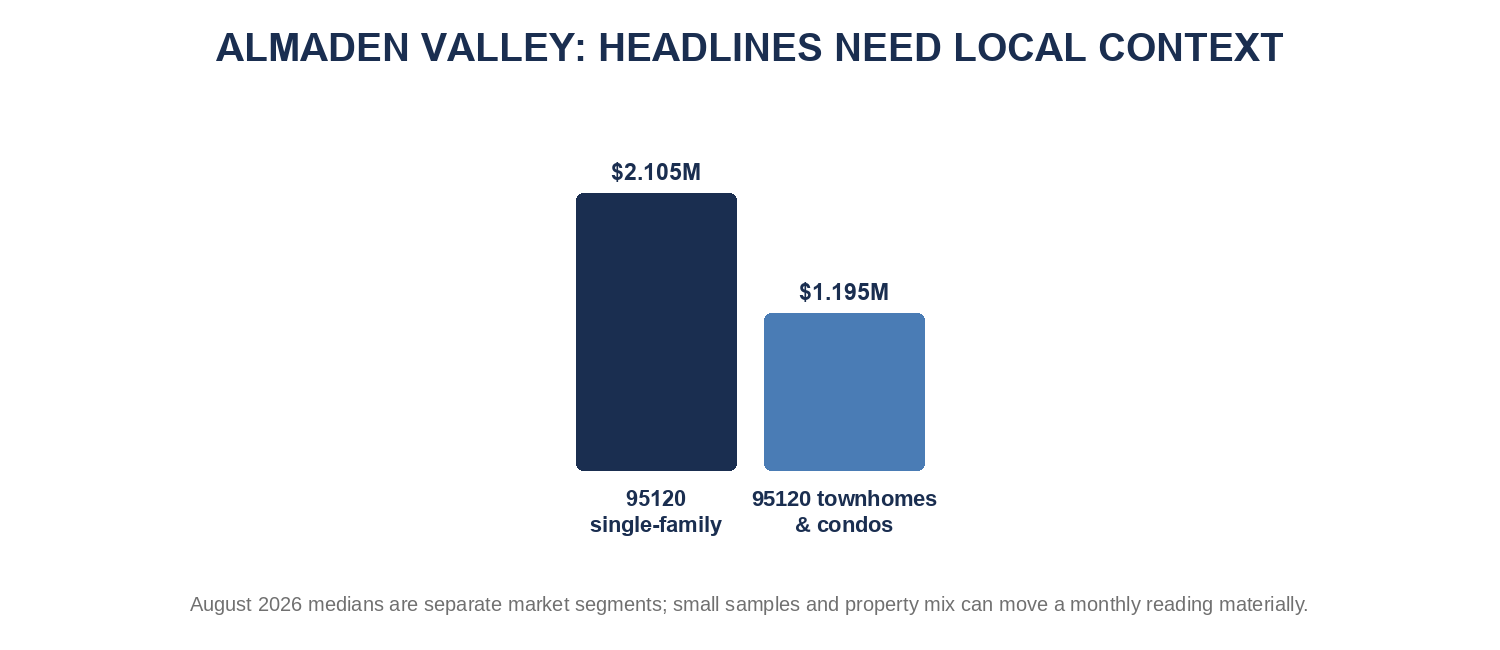
The $2.105M primary benchmark is not a valuation for every home in Almaden Valley. Street setting, school assignment, lot utility, condition, permits, HOA structure, and the specific competing set can move an individual result materially. The decision-useful question is not whether the entire area is strong or weak. It is which homes are earning urgency, which have become alternatives, and whether the reported monthly sample actually resembles the property being evaluated.
What this means:
- Homeowners and sellers: Compare the home with recent sales and current listings in the same school area or tract, with similar lot usefulness, condition, views, and access. The area-wide median is too broad to set the price.
- Buyers: The 77-day townhome-and-condo result came from three closings, so it is not automatic leverage. Compare the home with same-neighborhood alternatives, watch for a price change, missed offer date, or return to market, and confirm the seller's timing before seeking a better price or terms.
- Tim & Faye
|
|
|
Almaden Valley Market
The Local Pulse
|
|
August 2026 at a glance
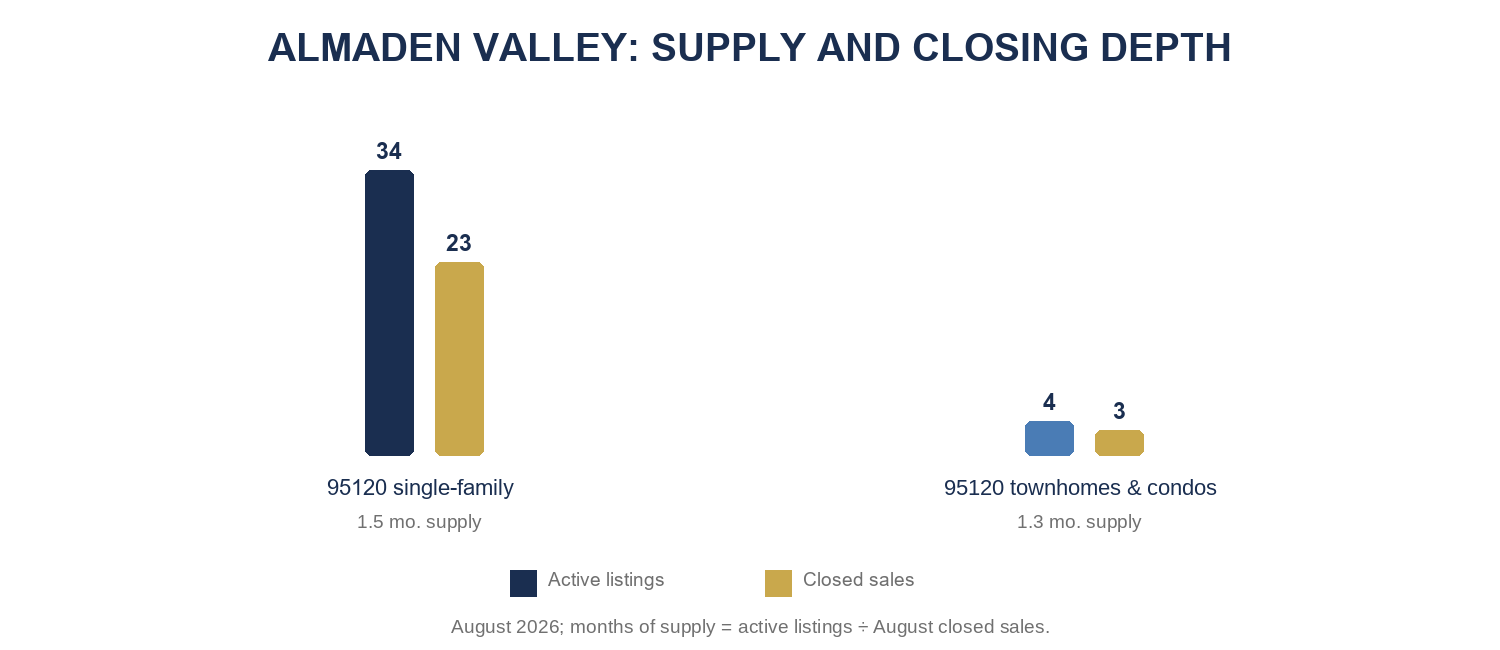
- Primary benchmark: 95120 single-family: $2.105M median; 23 closings; 10 median days; 101% sale-to-list; 1.5 months of inventory.
- Comparison signal: 95120 townhomes and condos: $1.195M median; 3 closings; 77 median days; 99% sale-to-list; 1.3 months of inventory.
- Selection and pace: Sample and selection: 26 closings across the shown market segments and 38 active listings; medians can be distorted when only a few homes sold or the mix of homes changed.
- Financing: the national 30-year fixed average was 7.28% on October 1. At that rate, 20% down on the $2.105M benchmark implies roughly $11,520 per month in principal and interest before taxes, insurance, and other costs. Pricing can differ by loan and borrower.
|
|
Financing & Affordability
What the October Rate Picture Means
|
|
Freddie Mac's national 30-year fixed average was 7.28% on October 1. With 20% down on the $2.105M benchmark, the illustrative principal-and-interest payment is about $11,520 per month, before property tax, insurance or other obligations. This is a planning illustration rather than a loan quote; pricing, points and borrower profiles can differ materially. The Federal Reserve raised its target range by one-quarter point on September 16; mortgage rates do not move one-for-one with that policy rate, so buyers should compare the actual fixed-rate, adjustable-rate, and buydown quotes available for their loan size.
C.A.R.'s second-quarter affordability index found that 22% of Santa Clara County households could afford the county's $2.05 million median single-family home. Its model required about $510,800 in annual income at a 6.54% effective rate. Almaden Valley's townhomes, conventional houses, and luxury or custom homes attract buyers with different budgets, down payments, and financing options; one regional employment headline cannot explain demand for all of them.
Many buyers are using adjustable-rate mortgages or temporary buydowns to reduce the initial payment while preserving the opportunity to refinance if fixed rates improve. That can be practical for a buyer with strong liquidity, expected income growth, or a defined holding period, but the adjustment schedule, rate caps, and future payment range should be compared with a fixed-rate option before offer day.
A targeted seller credit can sometimes address payment pressure more efficiently than a broad price reduction. Buyers should compare that benefit with the property's immediate repair, insurance, and ownership costs.
|
|
Market Behavior
What Is Moving
|
|
Entry-priced townhome — 1246 Charise Court. The three-bedroom, two-and-one-half-bath, 1,502-square-foot townhome closed August 6 for $1.01 million. It shows an Almaden Valley ownership entry point well below the single-family headline, but property type, HOA obligations, size, and condition remain essential to the comparison.
Near the single-family median — 6281 Desert Flame Drive. The four-bedroom, two-bath, 1,840-square-foot home closed August 24 for $2.105 million, matching August’s $2.105 million 95120 single-family median. It is a useful benchmark, not a substitute for comparing lot, condition, school assignment, and immediate competition.
Upper-market sale — 6570 Pfeiffer Ranch Road. The five-bedroom, five-and-one-half-bath, 3,551-square-foot home closed August 13 for $3.7 million. The result shows that larger, well-located Almaden Valley homes can attract buyers with different budgets and priorities than a typical resale.
|
|
Market Behavior
Where Activity Stalls
|
|
Hillside and custom homes with unresolved diligence. Insurance, access, slope, drainage, septic history, and rebuilding considerations can narrow the buyer pool.
Large homes with dated systems. Buyers distinguish cosmetic opportunity from a multi-year capital program.
Pricing from a small set of exceptional sales. Lot usability and school boundary can be more important than proximity alone.
|
|
Regional Comparison
AI Wealth: Relevant, Not the Whole Story
|
|
Almaden's demand is grounded in space, schools, open-space access, and an established ownership base. Regional technology wealth supports the upper end, but buyer decisions remain unusually property-specific.
AI liquidity may deepen the pool for renovated custom homes, yet it is unlikely to remove underwriting friction for insurance, hillside, or major-project properties.
| |
Our read: Almaden Valley's well-prepared single-family homes should remain resilient, while homes with condition, insurance or access questions will require sharper pricing. |
|
|
What Changes Next
Local Community Watch
|
|
Almaden Road construction is the immediate community change. San José scheduled pavement repair, refreshed striping and a protected bikeway between Almaden Expressway and McKean Road for fall 2026, including removal of most on-street parking along the corridor.
Why residents should care. The work should improve long-term safety and pavement condition, but nearby households and commuters may experience temporary lane, access and parking disruption during construction.
What to watch next. Watch the construction schedule, traffic handling and completion of the protected bikeway. This is a near-term quality-of-life and access issue, not a direct change in housing supply.
|
|
Six-Month Outlook
Our Base-Case View
|
| Segment |
Expected direction |
Why |
| Turnkey family homes |
Firm |
Clear utility and schools support demand. |
| Custom luxury |
Selective |
Small buyer pool and property-specific underwriting. |
| Hillside properties |
Negotiable |
Insurance and site diligence matter. |
| Dated large homes |
Price sensitive |
Renovation and carrying costs are explicit. |
|
|
Prediction: Almaden Valley should remain stable but selective through early 2027. Turnkey homes with clean documentation are likely to protect value, while hillside, custom, and renovation-heavy listings will show the widest negotiation ranges and longest timelines.
This is a market outlook, not a guarantee of future value. Property condition, micro-location, school assignment, lot, architecture, insurance, and financing can materially change an individual result.
|
|
Recommendations
What Matters Now
|
|
For homeowners:
- value against the correct school boundary, tract or custom segment, lot utility, and site profile.
- assemble insurance, roof, drainage, pool, solar, permit, and retaining-system records before selling.
- Treat the 77-day townhome-and-condo result as a three-sale sample, not an area-wide slowdown; use a longer set of same-tract, same-school, and similar-lot sales before changing a value estimate.
For sellers:
- For a hillside or custom home, resolve drainage, slope, access, insurance and permit questions before launch; then price from the same school area and lot type, not the highest nearby sale.
- show buyers the practical benefits of the home, including usable outdoor space, trail access, privacy, commute, and daily convenience.
- For hillside, custom, or large-lot homes, deliver drainage, slope, retaining-wall, access, insurance, and permit evidence before launch; unresolved site costs shrink the buyer group and the offer.
For buyers:
- separate ordinary updating from structural repairs, drainage or slope concerns, retaining walls, access problems, and insurance cost.
- When a custom or hillside home exceeds the 10-day house benchmark, negotiate only after pricing drainage, slope, access and insurance costs against same-school, similar-lot alternatives.
- For hillside or custom homes, price drainage, slope, retaining-wall, access, insurance, septic or well, and permit work before contingencies; those costs determine whether a negotiated price is actually favorable.
|
|