MARKET REPORT
The Local Pulse
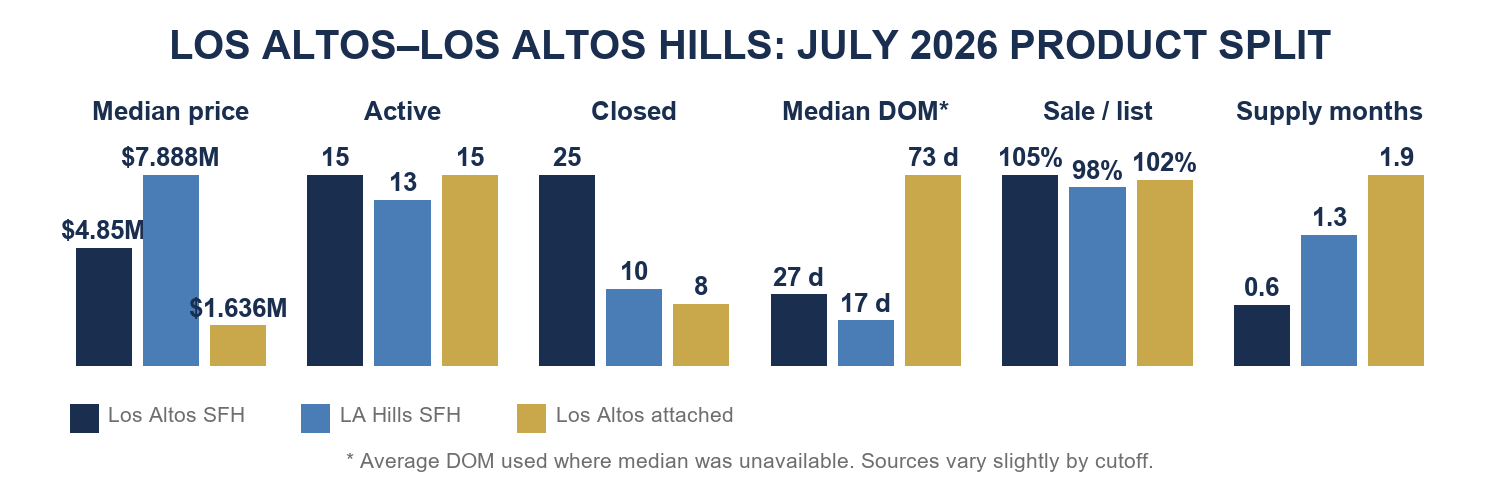
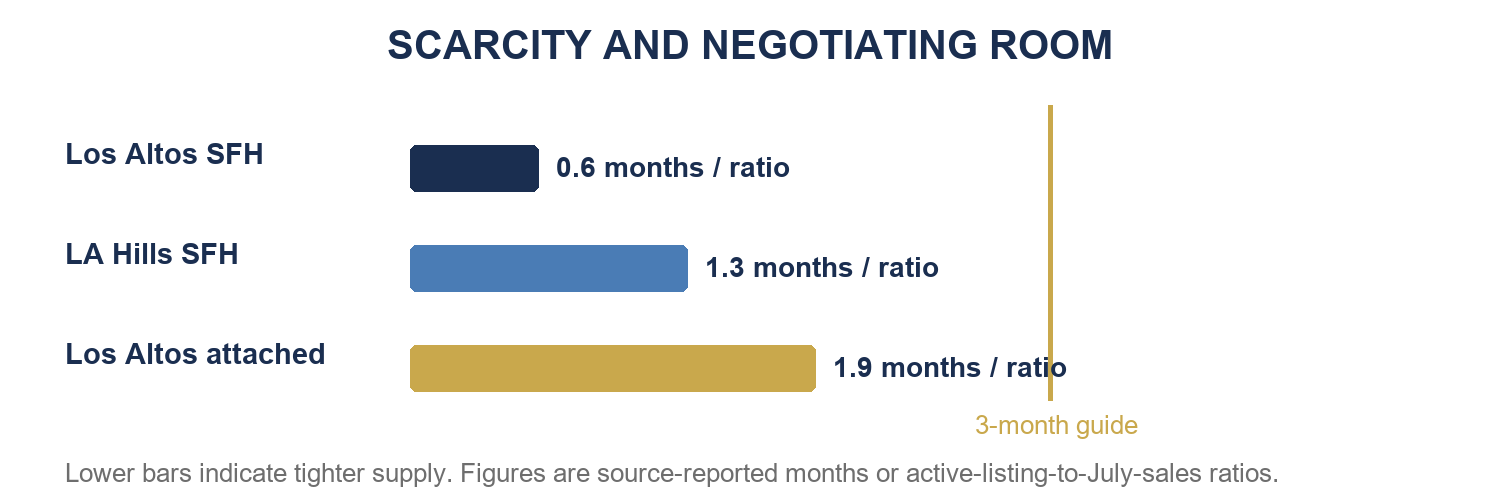
- Los Altos SFH: $4.85M median; 25 closings; 105% of list; 27 average days.
- Los Altos Hills SFH: $7.888M median; ten closings; 98% of list; 17 median / 22 average days.
- Los Altos attached: $1.636M median; eight closings; 73 average days; 102% of list.
- Combined Los Altos/Los Altos Hills detached inventory was roughly 0.8–0.9 of July sales, but the two areas should not be valued as one market.
What the September Rate Picture Means
Freddie Mac's national 30-year fixed average was 6.71% on September 3. With 20% down on the city's July single-family median, the illustrative principal-and-interest payment is about $25,060 per month, before property tax, insurance, HOA costs or other obligations. This is a planning illustration rather than a loan quote; jumbo pricing, points and borrower profiles can differ materially.
C.A.R.'s second-quarter affordability index found that 22% of Santa Clara County households could afford the county's $2.05 million median single-family home. The model required about $510,800 in annual income at a 6.54% effective rate. That county measure is broader than any one city, but it explains why liquidity, equity and financing structure are now central to local demand.
In Los Altos and Los Altos Hills, large down payments and jumbo loans are common, but financing is still property-specific. Appraisal support, insurability, site condition and the lender's treatment of unusual improvements can matter as much as the quoted rate. Buyers should complete that underwriting early rather than assume every high-equity purchase is interchangeable.
Many buyers are using adjustable-rate mortgages or temporary buydowns to reduce the initial payment while preserving the opportunity to refinance if fixed rates improve. The practical test is whether the adjustment schedule, rate caps and future payment range fit the household's broader plan - not whether the market promises a particular refinance date.
What Is Moving
Los Altos homes with walkability, schools, and a finished plan. Buyers reward scarce, easy-to-use properties and pay premiums when major systems and layout are resolved.
Los Altos Hills estates with exceptional site quality. Privacy, views, usable acreage, architecture, and documentation can still command deep demand, even when sale-to-list is below 100%.
Attached homes with house-like utility. Townhomes and condos can serve downsizers and entry buyers when the HOA, parking, privacy, and floor plan justify the price.
Where Activity Stalls
Attached inventory with a 73-day average. The long marketing time is a clear warning that buyers are comparing buildings and ownership costs carefully.
Hills estates priced from a single trophy sale. Ten monthly closings cannot support broad percentage conclusions; site and architecture dominate.
Properties with unclear development or resilience costs. Slope, drainage, pathways, fire, insurance, utilities, permits, and tree constraints can materially change the economics.
AI Wealth: A Local Reading
These communities are positioned directly in the Peninsula wealth corridor. AI and venture liquidity can deepen the buyer pool for rare estates and finished family homes, but supply is too heterogeneous for a uniform 'AI premium.'
The July data themselves show the distinction: Los Altos sold above asking while Los Altos Hills' very high median came with sales below asking. Scarcity and wealth support demand; property-specific underwriting still sets the result.
Forces to Watch
Los Altos infill. The city continues to process multifamily and El Camino projects, while its affordable-housing program reported 113 restricted units as of June 2026.
Los Altos Hills Housing Element. The town is implementing targeted multifamily rezoning and evaluating inclusionary policy while seeking to preserve rural character.
ADUs and multigenerational use. Secondary units can add flexibility and value, but feasibility depends on site, utilities, access, and local review.
Our Base-Case View
| Segment | Direction | Why |
|---|---|---|
| Los Altos turnkey SFH | Competitive | Low inventory and 105% of list. |
| LA Hills exceptional estates | Active | Wealth pool deep; property fit decisive. |
| LA Hills ordinary / dated | Negotiable | High carrying and project costs. |
| Los Altos attached | Selective | Long average marketing time. |
Prediction: The combined area should retain strong long-term demand, but reported medians will remain unstable. Los Altos turnkey homes are likely to show the most consistent competition. Los Altos Hills will produce occasional extraordinary sales alongside meaningful negotiation on properties with condition, site, or pricing friction.
This outlook is an informed opinion, not a guarantee. Property condition, micro-location, financing, schools, permits, insurance and broader economic conditions can materially change an individual result.
What Matters Now
- Homeowners: never apply the Los Altos Hills median to a property without a close site, location, and quality match.
- Homeowners: document improvements, utilities, paths/easements, drainage, fire work, tree work, and permits.
- Sellers: in Los Altos, align preparation with the first two-week competition window.
- Sellers: in the Hills, sell the site and execution certainty—not only the square footage.
- Buyers: compare total project and carrying cost on estates; a lower price can conceal a larger commitment.
- Buyers: use the slower attached segment to negotiate after reviewing HOA reserves, insurance, and assessments.
Choose this city report to receive future local updates.
GET THE LOS ALTOS–LOS ALTOS HILLS REPORT MONTHLY
Sources & Notes
- MLSListings / Aculist — Los Altos Hills
- City of Los Altos — Development Project Lists
- City of Los Altos — Affordable Housing
- Town of Los Altos Hills — Planning / Housing Element implementation
- Town of Los Altos Hills — Inclusionary Housing Policy
- SCCAOR — July 2026 county and city statistics
- SCCAOR — Q2 2026 city statistics
- Freddie Mac — Primary Mortgage Market Survey
- WIRED — AI equity and Bay Area housing
- The Guardian — AI wealth and San Francisco housing
- C.A.R. — July 2026 California Home Sales and Price Report
- C.A.R. — Q2 2026 Housing Affordability Index
- BLS — San Jose-Sunnyvale-Santa Clara Economy at a Glance
- BLS — August 2026 Employment Situation
City market figures use July 2026 unless stated otherwise. SCCAOR had not published August 2026 city statistics as of September 5, so July remains the newest complete official city period for this edition. Source cutoffs and property classifications can differ. Hero photography was supplied by Tim Alford for use in this report.
Christie's International Real Estate Sereno
214 Saratoga-Los Gatos Rd, Los Gatos, CA 95030
(408) 832-7698 · homes@alfordbon.com
Alford-Bon Team Website
TIM ALFORD DRE #01507448 · FAYE BON DRE #01746037 · SERENO GROUP, INC. DRE #02101181
Los Altos and Los Altos Hills belong in one regional discussion—but not in one price conclusion. July Los Altos single-family homes posted a $4.85 million median and 105% of list. Los Altos Hills reached a $7.888 million median but received 98% of list. Los Altos attached homes were a third, much slower segment.
The Hills median rose sharply from $5.725 million in Q2 to $7.888 million in July, but July contained only ten closings. That is a change in the mix of estates sold, not proof that every property appreciated at the same rate.
The decision framework must separate village/commute/school-driven Los Altos, acreage and estate-driven Los Altos Hills, and corridor/attached ownership. Each has a different buyer pool and different sources of risk.
— Tim & Faye